Retail Plaza and Strip Mall Appraisal in the GTA: How Income-Producing Retail Properties Are Valued
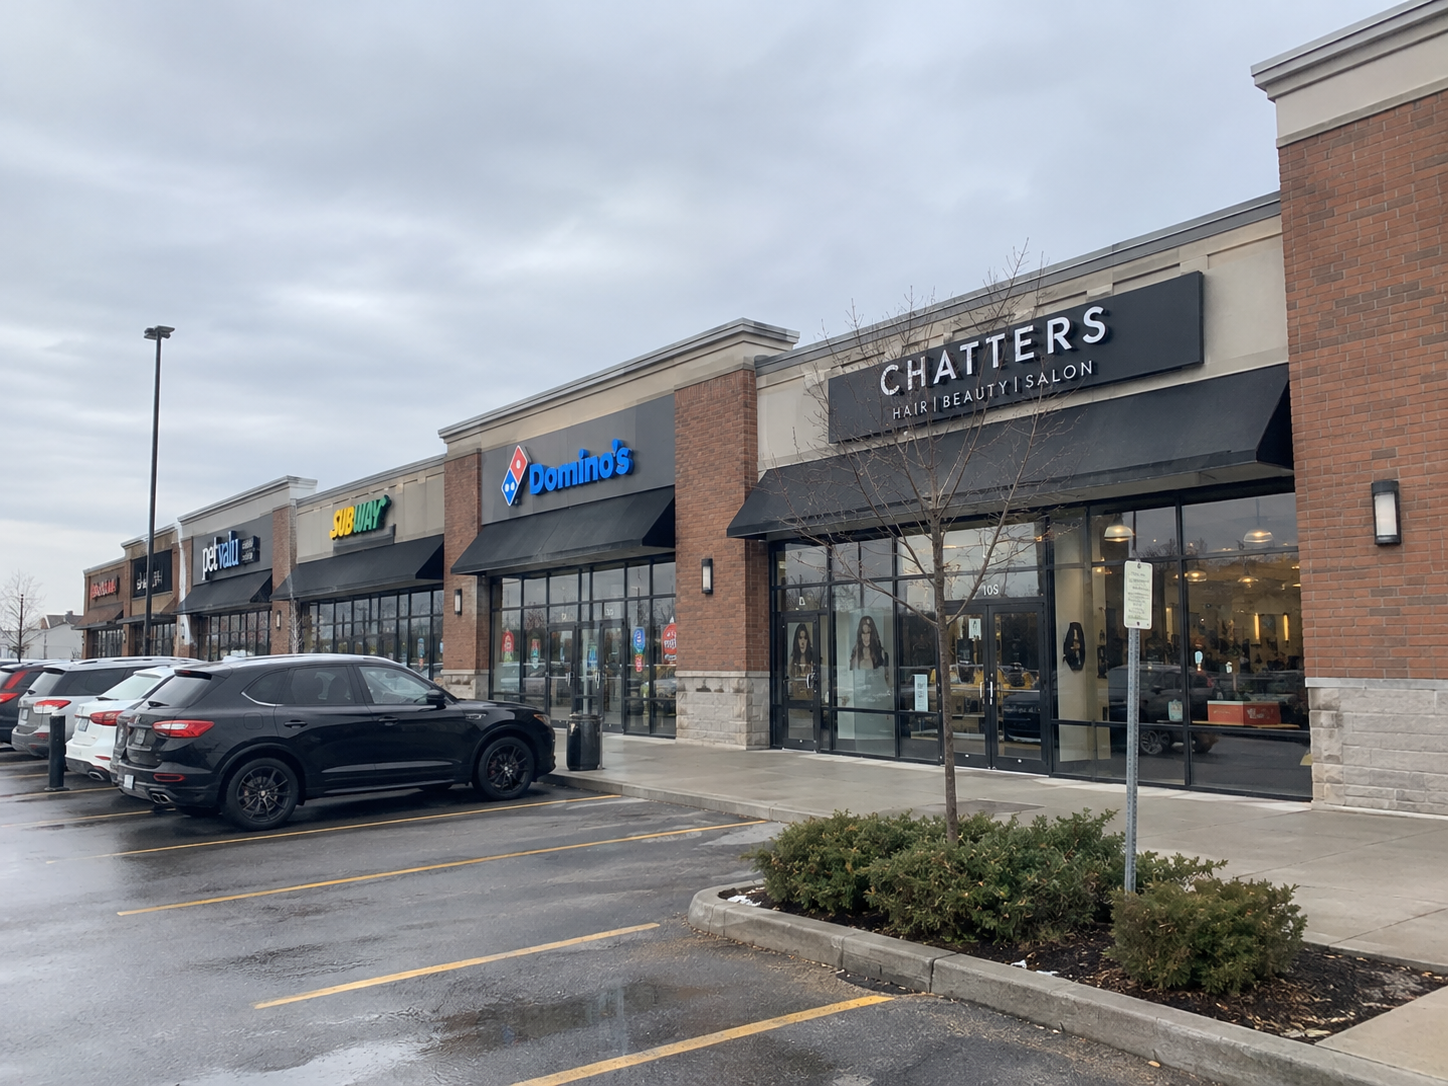
Most commercial appraisal articles talk about office towers and industrial parks. But if you have ever driven through Mississauga, Brampton, Richmond Hill, or any suburban GTA community, you already know what the dominant small-investor commercial asset actually looks like: a neighbourhood strip mall anchored by a pharmacy or grocery store, with a hair salon, a dental office, and a takeout restaurant filling the remaining bays.
These properties change hands regularly. They get financed, refinanced, challenged at MPAC, and passed down through estates. And every one of those transactions requires a proper appraisal. Yet most property owners arrive at that process with very little understanding of how an appraiser actually arrives at a number for a retail plaza.
This article covers exactly that. How retail plazas and strip malls are appraised in the GTA, what drives value, what creates risk, and what you need to prepare before you order a report.
What Qualifies as a Retail Plaza or Strip Mall for Appraisal Purposes
In the GTA market, retail plazas and strip malls generally fall into one of a few categories, and the category affects how the appraisal is structured.
A neighbourhood strip mall is typically a single-storey row of three to twelve retail units sharing a common parking lot. Tenants are usually service-based: personal care, food service, professional offices, convenience retail. These are the most common small-investor commercial properties in the 905 region.
A neighbourhood retail plaza is slightly larger, often anchored by a national or regional tenant such as a grocery chain, pharmacy, or dollar store, with smaller inline tenants filling the remaining bays. The anchor tenant drives foot traffic and often holds a long-term lease that becomes a significant component of the income analysis.
Power centres, enclosed malls, and large-format retail are separate categories with their own valuation methodology. This article focuses on the neighbourhood-scale assets that most private investors and family-owned commercial operators actually own in the GTA.
Why Retail Plaza Appraisals Are More Complex Than They Look
When someone orders an appraisal for a house, the process is relatively straightforward. Sales of comparable homes are analysed, adjustments are made, and a value is concluded. Retail plazas work differently because the value is not primarily driven by what the building looks like. It is driven by what the building earns.
A 10,000 square foot strip mall in Mississauga with strong tenants on long leases at market rent is worth considerably more than the identical building next door with below-market leases, a vacancy, or a tenant on a month-to-month arrangement. The physical asset is the same. The income stream is not. And in commercial appraisal, the income stream is the value.
This is why appraising retail plazas requires more document collection, more financial analysis, and more market research than a residential assignment. It is also why the appraisal fee for a retail plaza is higher, and why the turnaround time is longer. The appraiser is not just inspecting a building. They are underwriting a business.
The Three Approaches to Value — and Which One Carries the Most Weight
The Income Approach
For income-producing retail properties, the income approach is almost always the primary method of valuation. The core question the income approach answers is: given the rental income this property generates, what would a rational investor pay for it today?
The appraiser starts by establishing the effective gross income. This means reviewing the actual rent being collected from each tenant, identifying any vacancies, and then comparing those rents against current market rents for comparable retail space in the same submarket.
This step matters more than most owners realise. If a tenant signed a lease five years ago at $18 per square foot and the current market rate for that bay is $28, the appraiser will note the below-market rent as a leasing risk factor. Conversely, if a tenant is paying above-market rent, that lease is worth less than it appears on paper because the renewal risk is high.
From gross income, the appraiser deducts vacancy and credit loss (typically 5% to 10% in a stabilised GTA retail market, higher if the building has a history of turnover), and then deducts operating expenses. Depending on the lease structure, operating expenses may be passed through to tenants as additional rent. A triple-net lease, where the tenant pays property taxes, insurance, and maintenance directly, leaves the landlord with a cleaner net income figure. A gross lease puts those costs on the landlord, which reduces net income and affects value.
The resulting net operating income (NOI) is then capitalised using a market-derived cap rate. Cap rates for GTA neighbourhood strip malls and retail plazas in 2025 and 2026 have ranged from approximately 5.0% to 7.5%, depending on location, tenant quality, lease term, and building condition. A property in a dense Mississauga commercial corridor with a national anchor tenant on a 10-year lease will trade at a significantly lower cap rate than a property in a secondary location with month-to-month tenants.
The capitalised value formula is straightforward: NOI divided by cap rate equals value. A plaza generating $250,000 in NOI capitalised at 5.5% produces a value indication of approximately $4.5 million. The same NOI at a 7.0% cap rate produces a value closer to $3.57 million. That spread illustrates exactly why cap rate selection is the most consequential single decision in a retail plaza appraisal.
The Direct Comparison Approach
The appraiser will also look at comparable sales of retail plazas in the GTA market. This is more challenging than residential comparison because commercial sales are less frequent, less uniform, and less publicly documented. The appraiser needs to source verified sales data from brokerage networks, CoStar, and industry contacts, and then adjust for differences in size, location, tenancy, lease term, and building condition.
In a well-supported assignment, the direct comparison approach either confirms the income approach result or flags a significant discrepancy that requires explanation. If comparable sales are consistently trading at $300 per square foot and the income approach is producing $200 per square foot, there is a reconciliation question that the appraiser must address in the report.
The Cost Approach
The cost approach, which estimates what it would cost to replace the building, is given limited weight for income-producing retail properties. Its primary application is for newer construction where depreciation is minimal, or for properties where the income and comparison approaches are difficult to support due to limited market data. For most GTA strip malls and retail plazas, it serves as a reasonableness check rather than a primary value indicator.
What the Appraiser Needs from You
One of the most common delays in retail plaza appraisals is incomplete documentation. The appraiser needs financial and legal information that is not visible from a site inspection. The sooner you provide it, the faster the report can be completed.
You will typically be asked to provide the current rent roll, which shows each tenant, their unit size, their base rent per square foot, the lease start and expiry date, and any rent steps or renewal options. You will also need to provide the most recent operating statements, generally two to three years of actuals plus a current-year budget. The appraiser will want to see how property taxes, insurance, utilities, maintenance, and management fees have been tracking.
If any leases have been renewed, amended, or extended in the past 24 months, those documents should be included. The same applies to any outstanding capital expenditures such as a roof replacement, parking lot resurfacing, or HVAC work. These affect the building’s net income, its remaining useful life, and the deferred maintenance deduction that the appraiser may apply.
If the property has a vacancy, be prepared to share what the last tenant paid, how long it has been vacant, and what efforts have been made to re-let. A long-term vacancy in a secondary bay is a different risk signal than a recently vacated unit with active leasing interest.
How Location Affects Retail Plaza Value in the GTA
In residential appraisal, location is a factor. In retail appraisal, location is often the whole story.
A strip mall on a high-traffic arterial road in Mississauga with strong daytime population density, easy access from both directions, and a large surface parking lot commands a fundamentally different cap rate than a comparable building on a secondary road with lower visibility. Tenants know this, which means the difference shows up in market rents, lease length, and renewal probability.
The GTA retail market has also seen significant variation by submarket over the past several years. Areas with strong population growth driven by new residential development have seen retail plaza vacancy compress significantly as service retail demand follows new rooftops. Areas where a major anchor tenant has departed, particularly in older plazas that were anchored by a department store or large-format retailer, face a different set of challenges entirely.
Transit access has become an increasingly relevant factor as Metrolinx continues to expand rail and LRT connections across the GTHA. A retail plaza within walking distance of a new GO station or LRT stop carries potential for both near-term intensification and medium-term land value appreciation that an appraiser in a highest and best use analysis will consider.
The Lease Structure Question: Why Not All Rents Are Equal
One of the more nuanced aspects of retail plaza appraisal is understanding what the lease actually says, not just what the rent cheque says.
A tenant paying $25 per square foot on a gross lease, where the landlord covers all operating costs, is a fundamentally different income stream than a tenant paying $25 per square foot on a triple-net lease where the tenant covers taxes, insurance, and maintenance. The net income to the landlord in those two scenarios is very different, and the appraiser must normalise the income figures to reflect the actual economics of each lease arrangement.
Percentage rent clauses, common in leases with retail anchors, add another layer. If a grocery store tenant pays a base rent plus a percentage of sales above a stated threshold, the appraiser needs to assess the likelihood of that overage rent materialising and how to treat it in the income analysis.
Lease term remaining is also a significant factor. A plaza where every tenant has fewer than two years left on their lease carries substantially more re-leasing risk than one where the majority of tenants are committed for five to ten years. Re-leasing risk means potential vacancy, tenant improvement costs, leasing commissions, and potentially below-market rents during a lease-up period. All of that translates directly into a higher cap rate, which means a lower value.
Retail Plaza Appraisals for Specific Purposes
Financing
Most commercial lenders require a third-party CUSPAP-compliant appraisal before advancing funds on a retail plaza purchase or refinance. The appraisal establishes the lending value, which is the figure the lender uses to calculate the loan-to-value ratio. For most conventional commercial mortgages, lenders will advance 65% to 75% of appraised value.
It is worth noting that the lender’s appraiser is instructed to be conservative. Lenders want a value that accounts for downside scenarios, not just current market conditions. If you are refinancing and the appraisal comes in below your expectations, the most common reasons are above-market rents that were discounted, a higher-than-market vacancy allowance applied to a secondary unit, or a cap rate that reflects current market uncertainty rather than the historical rate at which you purchased the property.
Sale
When selling a retail plaza, an independent appraisal before listing helps establish a realistic asking price grounded in the income the property actually generates rather than the income a motivated seller hopes it might generate. It also prepares you for the due diligence process, since any serious buyer will commission their own appraisal and you want to be able to defend your numbers.
MPAC Assessment Appeal
Municipal Property Assessment Corporation assessments on retail plazas are frequently challenged, and for good reason. MPAC uses a mass appraisal methodology that often misapplies cap rates or uses income figures that do not reflect the actual economics of a specific property. A professional appraisal that documents the actual income, actual vacancy, and appropriate cap rate for your specific submarket is the most effective tool in a property assessment appeal.
Estate and Probate
If a retail plaza is part of an estate, the value must be established at the date of death for probate purposes and for calculating any capital gains tax owing. Retroactive appraisals to a historical valuation date are a recognised and accepted practice, and an AACI-designated appraiser can provide an opinion of value for a past date based on market data from that period.
Matrimonial and Partnership Disputes
When a retail plaza is jointly owned and the owners are separating, an independent appraisal is required to establish fair market value for the purposes of a buyout or court proceeding. These assignments often require the appraiser to provide testimony or a report that can withstand cross-examination.
Common Valuation Issues Specific to GTA Retail Plazas
A few issues come up repeatedly in GTA retail plaza appraisals that owners and investors should be aware of before ordering a report.
Below-grade net rents are a frequent problem in older neighbourhood plazas where rents were set during a weaker market cycle and have never been brought up to current levels. The appraiser will apply market rents in the income analysis rather than actual rents, which can produce a stabilised value that differs from what a naive buyer might calculate from the current rent roll alone.
Deferred maintenance is another recurring issue. Parking lots, flat roofs, and HVAC systems in older plazas frequently have deferred capital needs that the appraiser must acknowledge. These are typically reflected either as a deduction from the capitalised value or as a higher vacancy and credit loss allowance to account for the risk that tenants may not renew in a building that requires significant investment.
Environmental issues occasionally surface in older retail plazas, particularly those with underground storage tanks from former automotive or petroleum tenants. An appraiser will flag any visible environmental concerns and recommend a Phase 1 or Phase 2 Environmental Site Assessment if warranted. Lenders will not advance funds on a property with outstanding environmental liability.
Zoning and intensification potential is increasingly relevant in the GTA given the density policies now embedded in the provincially approved Official Plans. A retail plaza on an arterial road in a designated intensification corridor has land value that exceeds the value of the existing income stream, and a highest and best use analysis in the appraisal will capture that. For some owners, the land value for a future mixed-use development exceeds what the property is worth as a going-concern retail plaza, and that changes the conversation about whether to hold, sell, or redevelop.
How Long Does a Retail Plaza Appraisal Take
A straightforward neighbourhood strip mall with three to six tenants and complete documentation typically takes ten to fifteen business days from the inspection date to the delivery of a completed report. More complex properties with multiple tenants, anchor lease analysis, or a highest and best use question involving intensification potential will take longer.
Delays almost always come from one of two places: incomplete document delivery from the owner, or difficulty sourcing comparable sales data in a thin market. Providing a complete rent roll and operating statements at the time of engagement is the single most effective way to keep the timeline on track.
What Makes an AACI-Designated Appraiser the Right Choice for Retail Plaza Work
Not every appraiser is qualified to value an income-producing retail property. The AACI designation, granted by the Appraisal Institute of Canada, is specifically designed for commercial, industrial, and investment property valuation. It requires advanced education, supervised experience, a comprehensive demonstration report, and ongoing professional development.
Lenders in Canada will not accept commercial appraisal reports from non-designated appraisers for mortgage purposes. Courts require AACI designates for litigation-related valuation opinions. And anyone purchasing, selling, or financing a retail plaza deserves an opinion of value from someone who works with income-producing properties regularly, not someone who appraised three strip malls last year in between residential assignments.
At IPS, our commercial appraisal work covers retail plazas, strip malls, and neighbourhood shopping centres across the GTA including Mississauga, Brampton, Vaughan, Richmond Hill, Markham, and Scarborough. Every commercial report is prepared or supervised by Ehsan Hassani, P.App., AACI, P.Eng., MBA.
Frequently Asked Questions
How much does a retail plaza appraisal cost in Toronto?
Fees for a retail plaza appraisal in the GTA typically range from $3,500 to $8,000 depending on the size of the property, the number of tenants, the complexity of the lease structure, and the turnaround time required. Contact us for a specific quote based on your property.
What is a cap rate for a retail plaza in Mississauga?
Cap rates for neighbourhood strip malls and retail plazas in Mississauga currently range from approximately 5.0% to 7.0%, depending on location, tenant quality, and lease term. Strong anchor tenancy and long remaining lease terms compress cap rates. Secondary locations and short-term or month-to-month tenancy push them higher.
Can I get a retail plaza appraised for MPAC appeal purposes?
Yes. A professional appraisal from an AACI-designated appraiser is the standard evidence used in a Request for Reconsideration or Assessment Review Board hearing. The appraisal documents the actual income, appropriate vacancy, and market cap rate for your specific property, which often differs significantly from what MPAC has applied in their mass appraisal model.
Do I need an appraisal to refinance a retail plaza?
Yes. All conventional commercial lenders require a CUSPAP-compliant appraisal from a designated appraiser before advancing funds. Some lenders maintain an approved panel of appraisers. It is worth confirming with your lender before ordering the appraisal that your chosen appraiser is on their approved list.
What if my plaza has a vacancy — will that hurt the appraisal?
A current vacancy will be reflected in the income analysis, but it does not necessarily reduce the appraised value dollar-for-dollar with the lost rent. The appraiser applies a stabilised vacancy assumption based on market conditions, which may be lower than your actual vacancy if the market evidence suggests the unit will lease up. They may also apply a lease-up adjustment that accounts for the cost and time required to fill the space at current market rates.
Can the appraisal consider the land value for future redevelopment?
Yes. If the property is located in a designated intensification area or has zoning that allows higher density development, the appraiser will conduct a highest and best use analysis that considers whether the current retail use or a future development scenario produces a higher value. In some GTA locations, particularly along major transit corridors, the land value as a development site now exceeds the income value of the existing retail plaza.
IPS provides CUSPAP-compliant commercial appraisal services for retail plazas, strip malls, and neighbourhood shopping centres across the Greater Toronto Area. Contact us to discuss your property and receive a fee estimate